Brand Fit Snapshot
Best for:
Not ideal if:
Similar properties you might like:
Quick assessment - takes 30 seconds
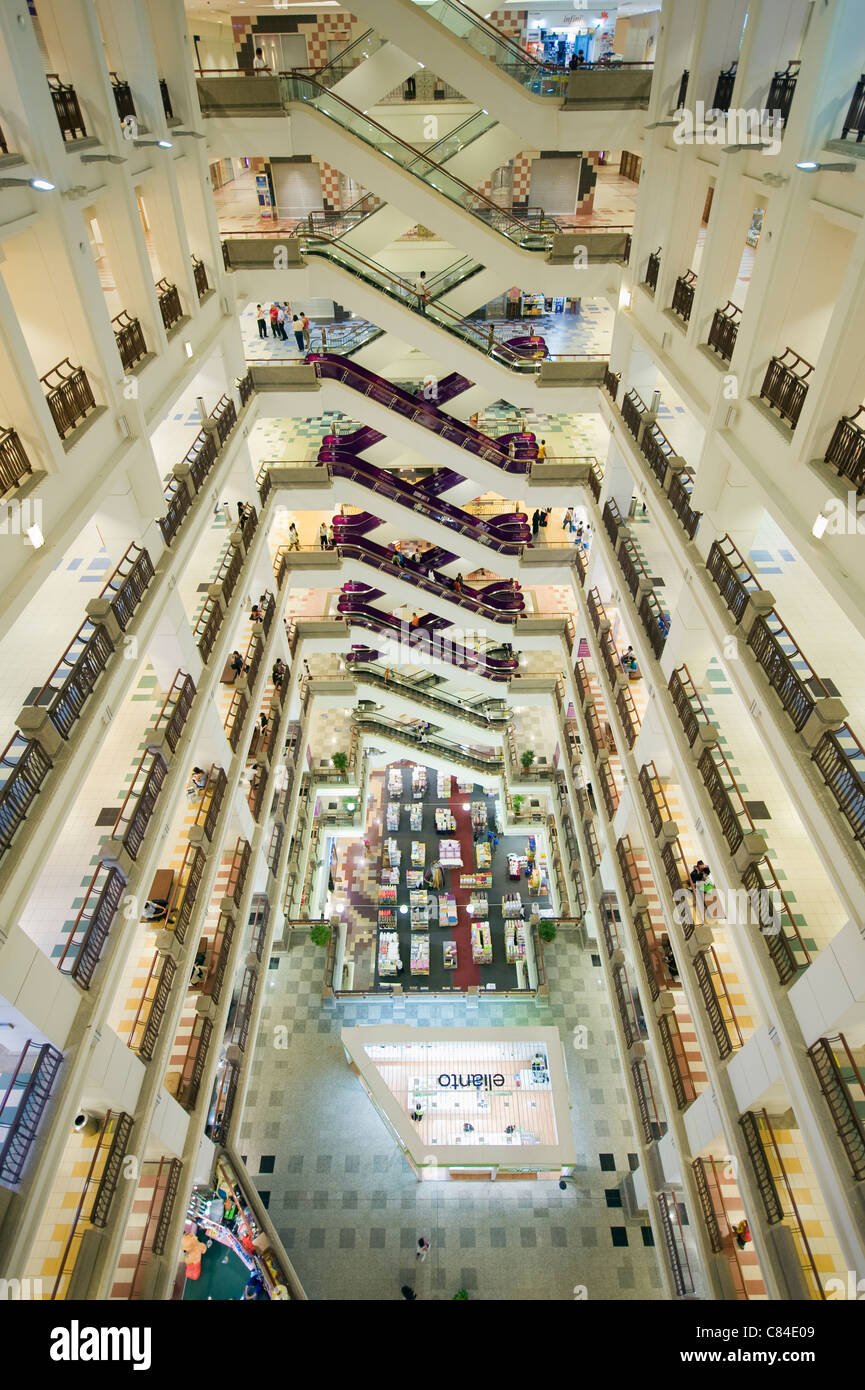
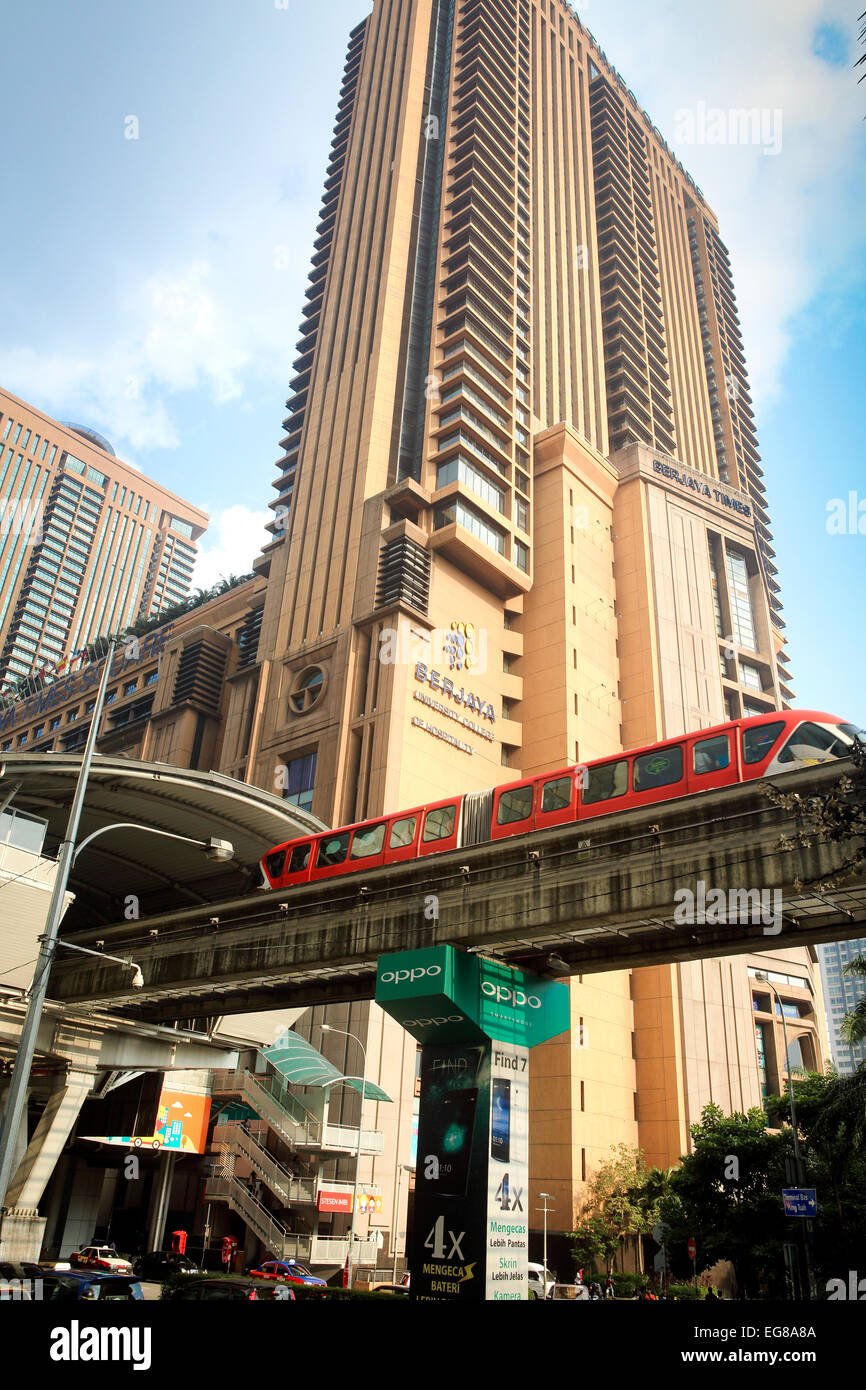
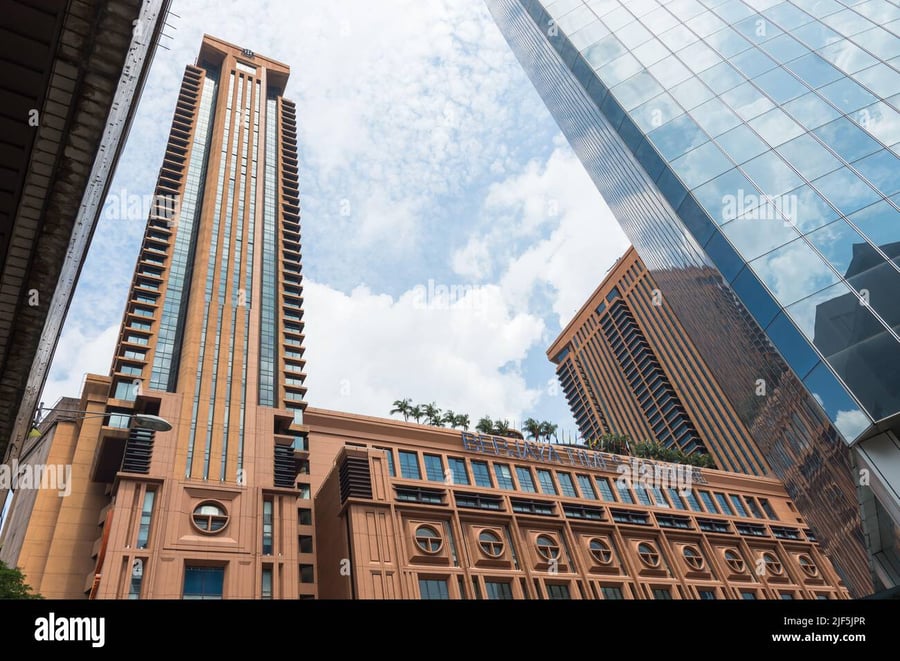
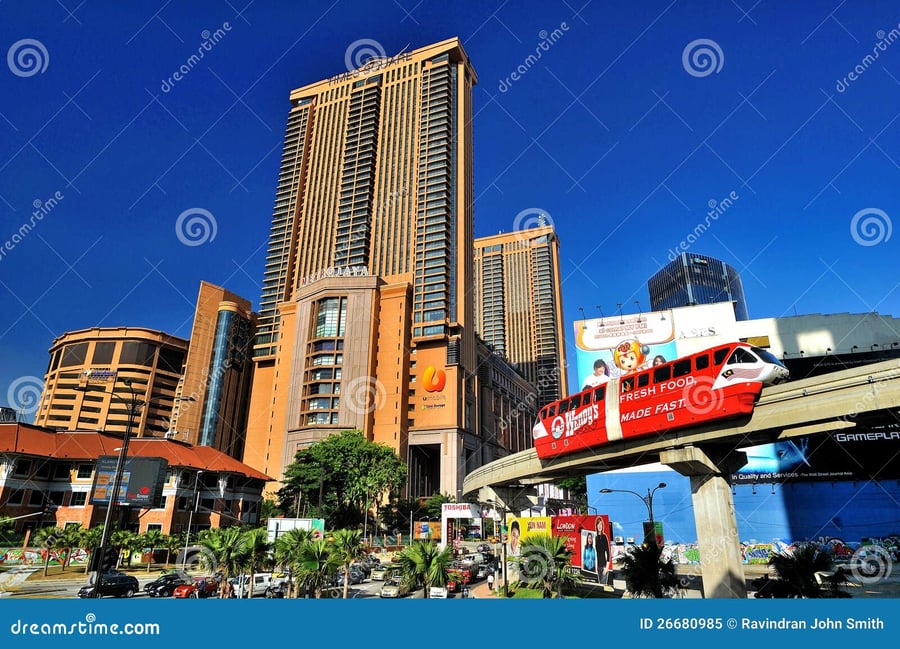
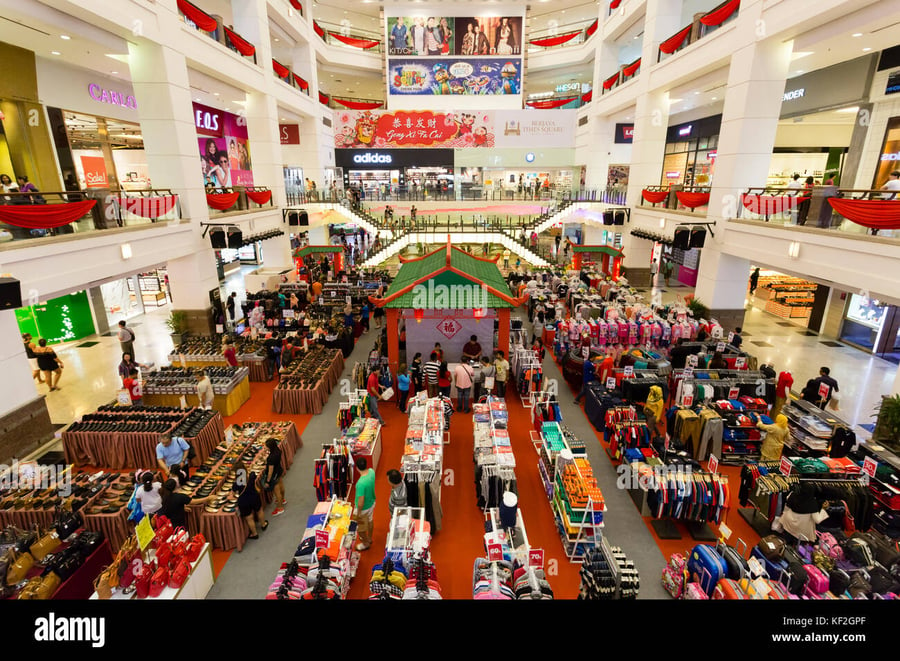
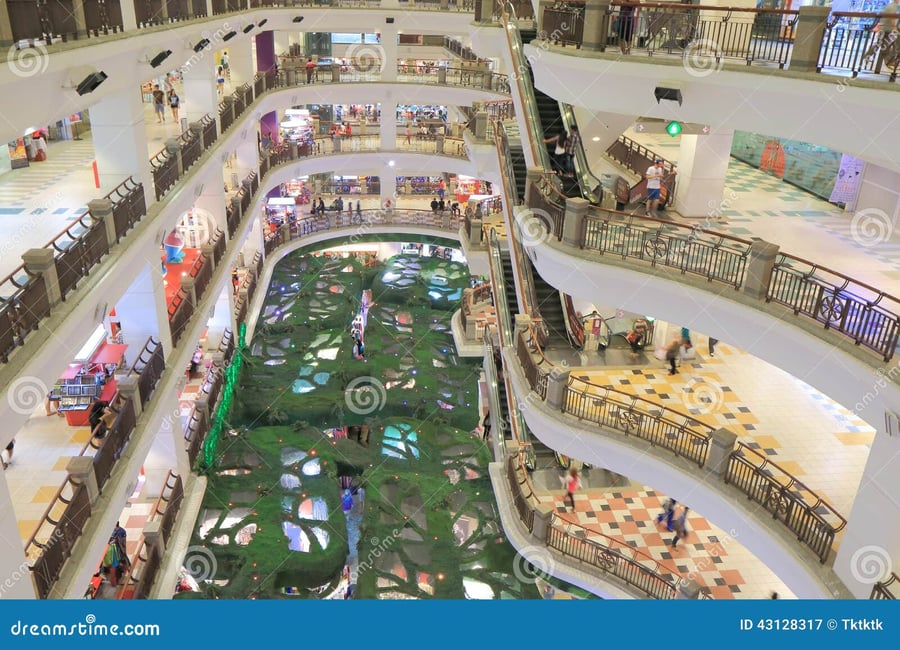
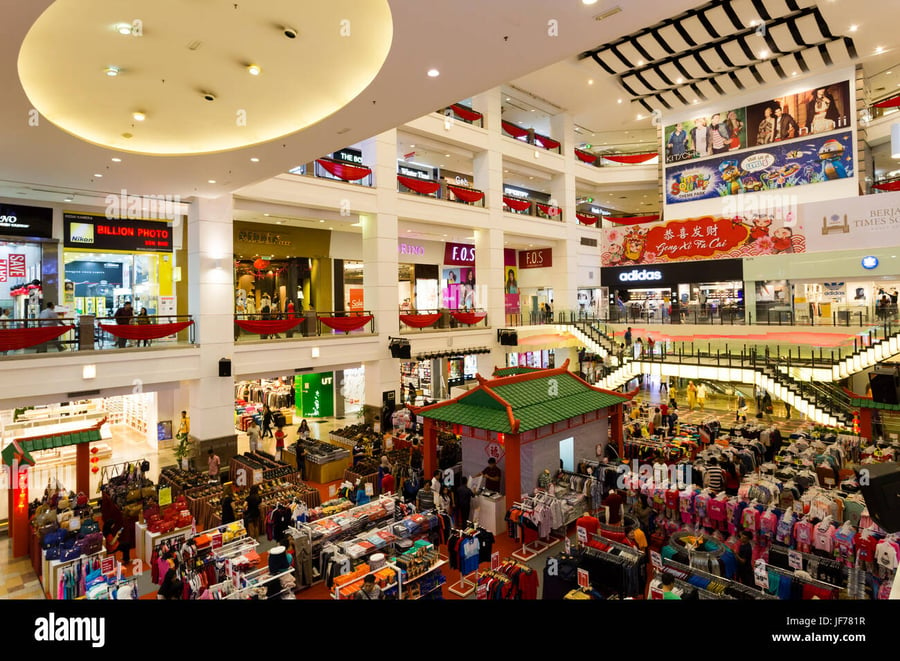
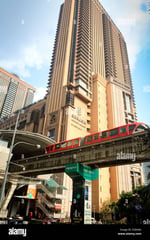
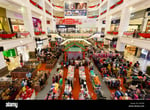
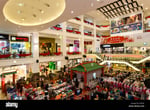
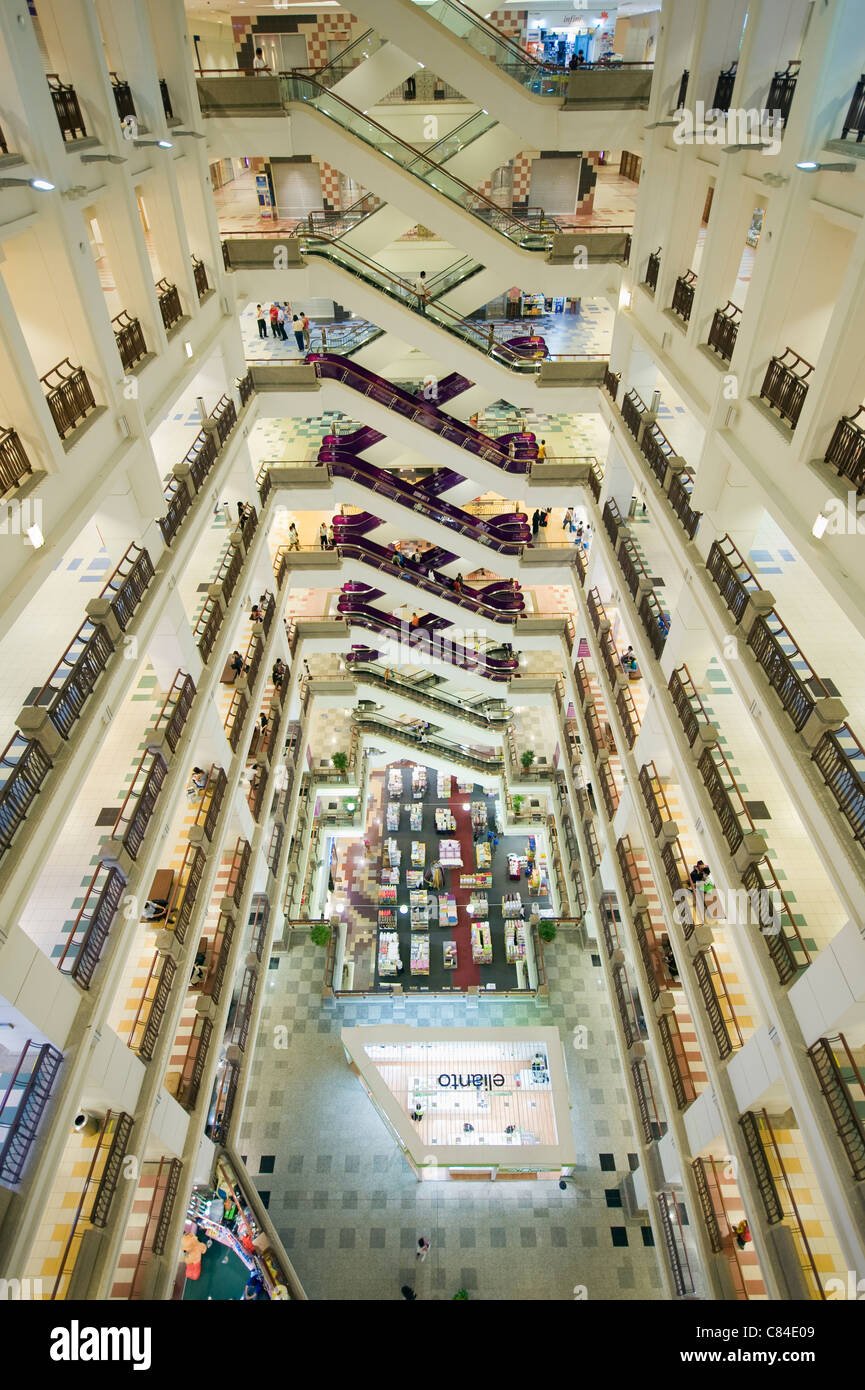
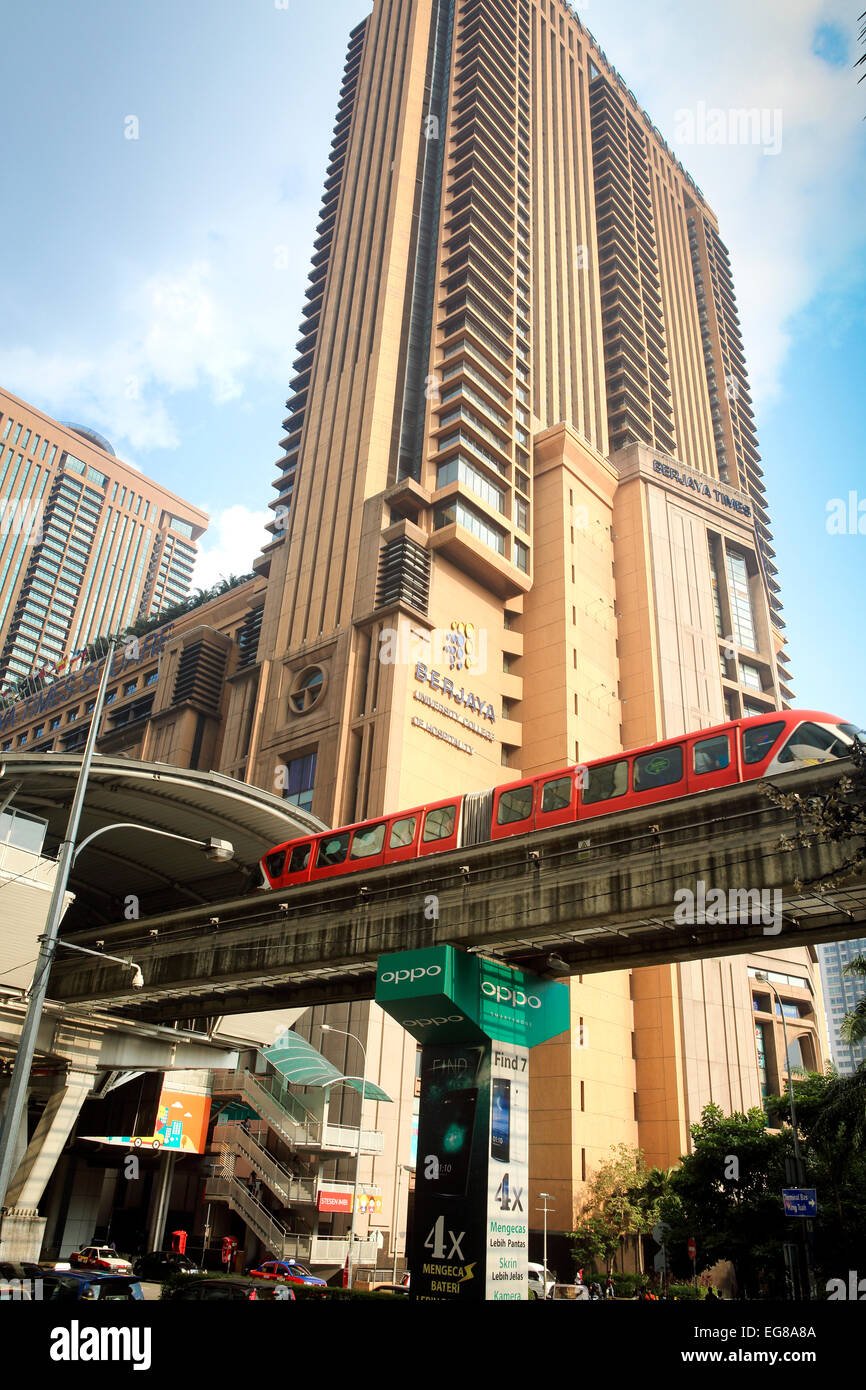
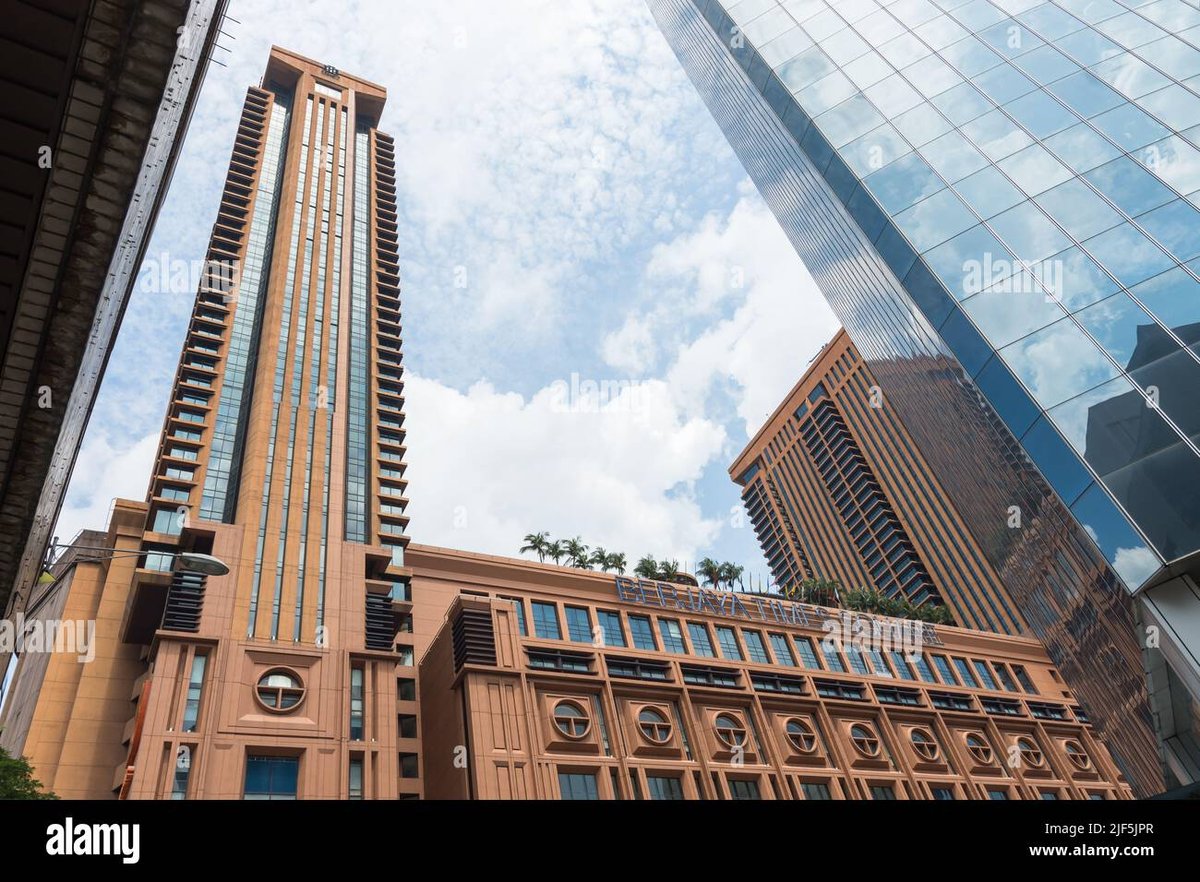
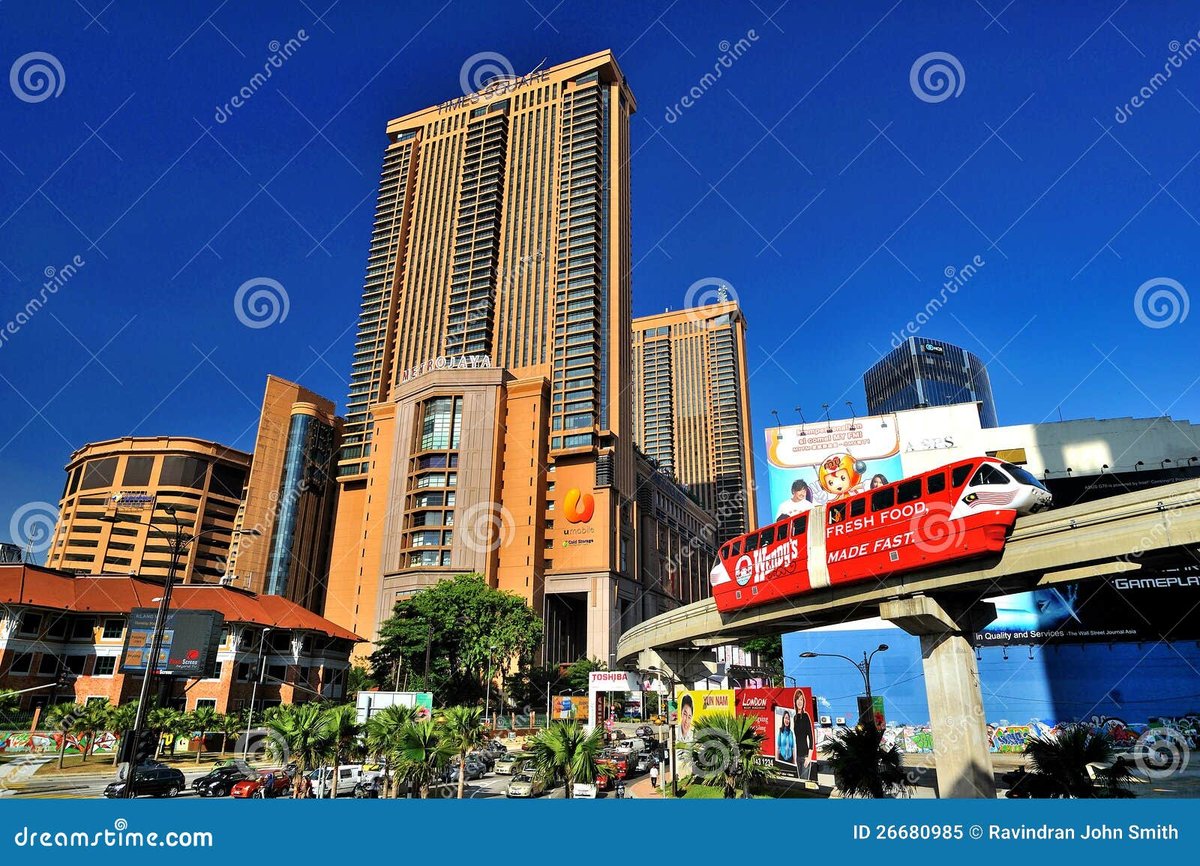
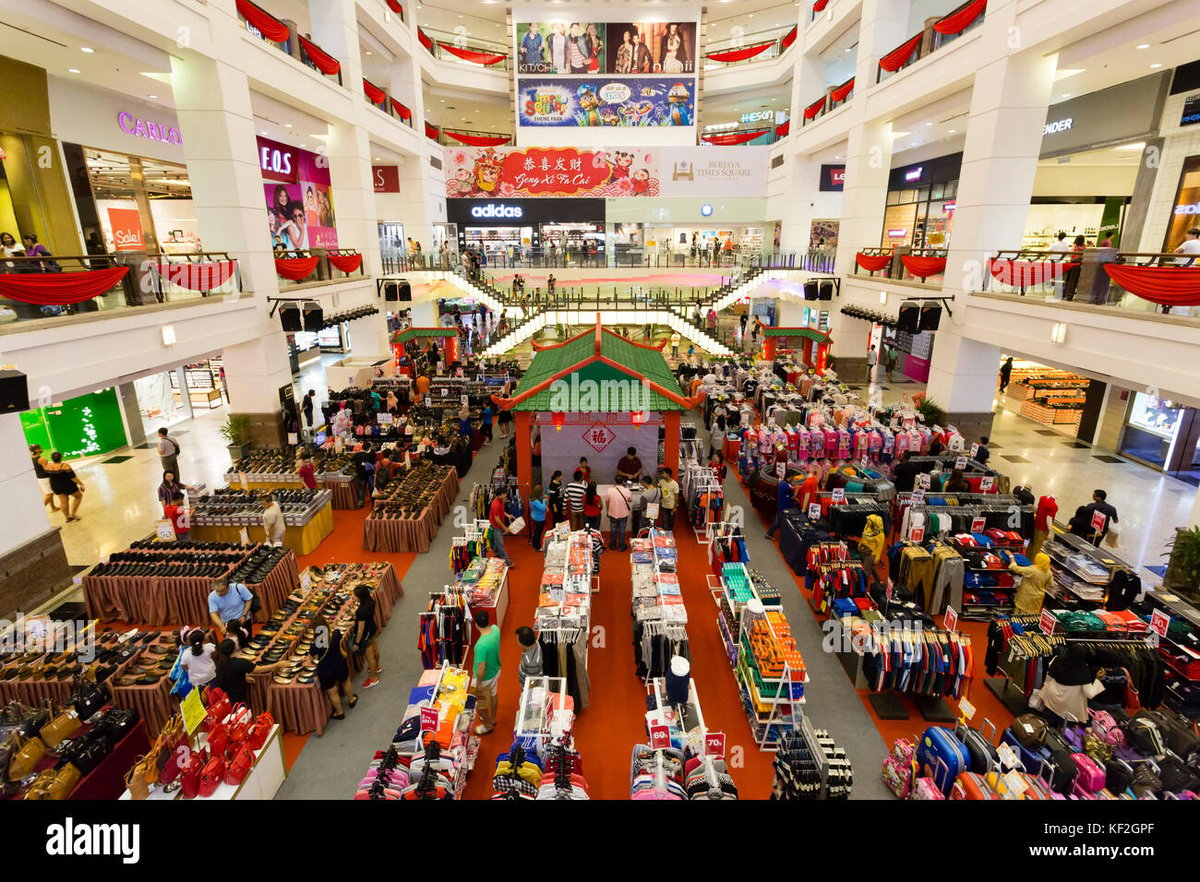
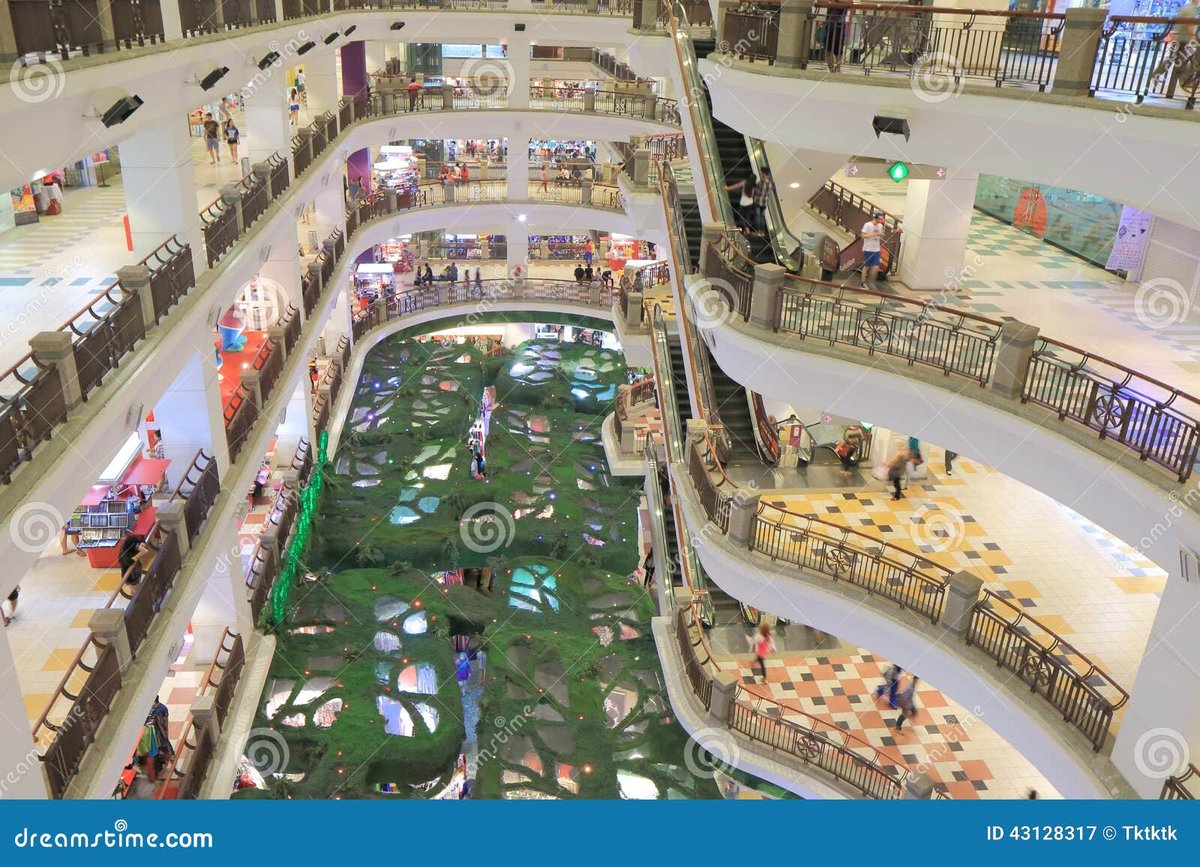
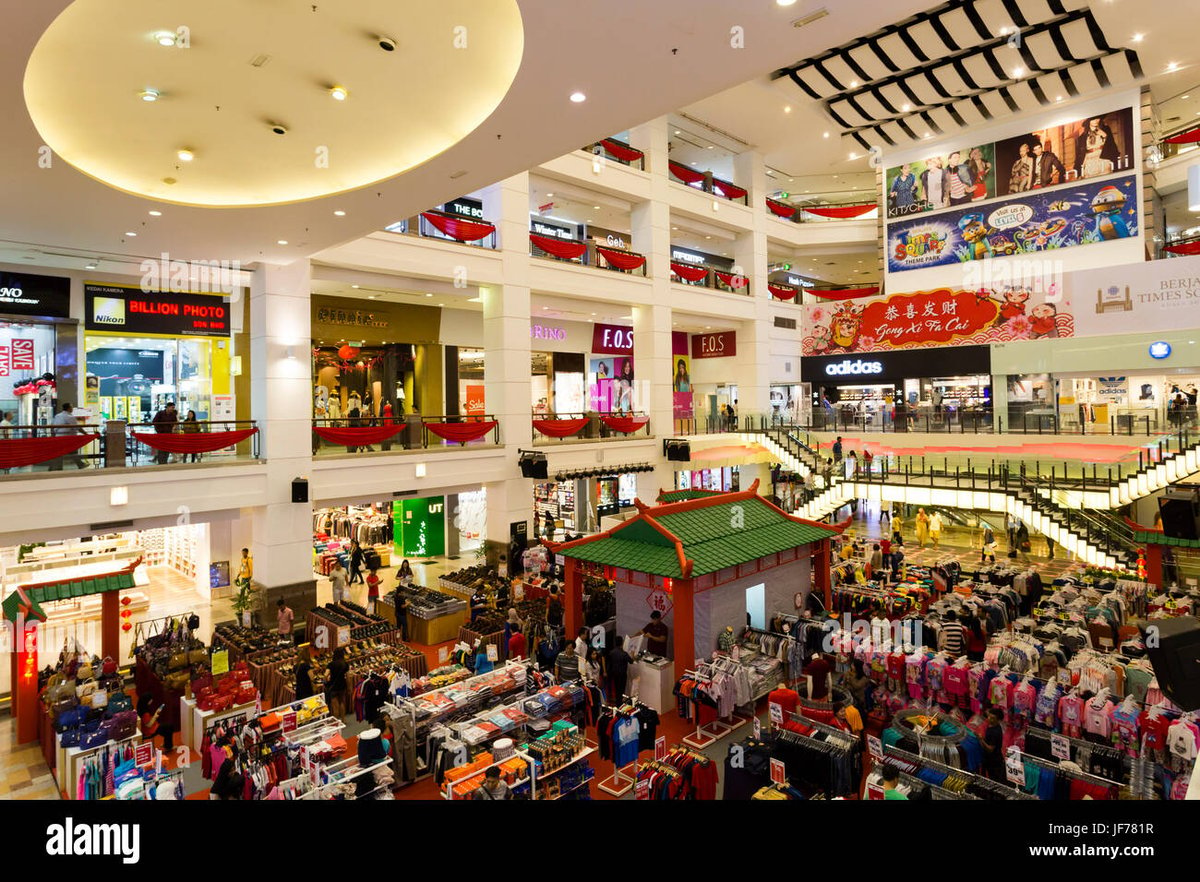
Berjaya Times Square is a mixed-use development in Bukit Bintang, Kuala Lumpur, featuring a 2.7 million sq ft shopping mall within a 7.5 million sq ft total built-up area. Opened in 2003, it includes over 1,000 retail outlets, 65 food and beverage options, office spaces, a hotel, and Southeast Asias largest indoor theme park, attracting families and tourists. The property benefits from central accessibility via Imbi Monorail station and proximity to major attractions like Pavilion KL.
In the Greater KL retail market, which added 1.1 million sq ft of space in 2024 and expects further supply in 2025, Berjaya Times Square maintains an estimated occupancy of 85%, aligning with the citys average of 84.3% as of Q2 2025 per JLL reports.
Tenant mix emphasizes mid-tier fashion, electronics, F&B, and entertainment, with brands like 7-Eleven, 4Fingers Crispy Chicken, and local outlets, supporting a balanced category distribution that includes 30% fashion, 25% F&B, 20% general merchandise, and 25% services/leisure based on directory analysis.
Market position as a value-oriented destination appeals to middle-income locals (household income RM5,000-10,000) and international visitors, bolstered by Malaysias 28.2 million tourist arrivals in Jan-Aug 2025.
Leasing advantages include flexible terms with base rents averaging RM12-15 per sq ft per month, turnover rents at 5-7% of sales, and incentives like rent-free periods of 3-6 months for anchor tenants, per Savills 1H 2024 data. However, challenges arise from parent company Berjaya Corporations FY2025 revenue decline to RM9.34 billion and net losses, signaling operational pressures. Footfall estimates at 10-12 million annual visitors, driven by theme park (14 attractions) and events, though post-pandemic recovery shows 5-7% YoY growth amid KLs retail sales up 5.6% in Q1 2025.
Risks include aging infrastructure requiring capex for upgrades and market saturation in Bukit Bintang with 15+ competing malls within 2 km radius.
Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
Hours of Operation
Hours
| Monday | 10:00 AM — 10:00 PM |
| Tuesday | 10:00 AM — 10:00 PM |
| Wednesday | 10:00 AM — 10:00 PM |
| Thursday | 10:00 AM — 10:00 PM |
| Friday | 10:00 AM — 10:00 PM |
| Saturday | 10:00 AM — 10:00 PM |
| Sunday | 10:00 AM — 10:00 PM |
Hours may vary on public holidays. Check with individual stores for specific holiday schedules.
Insights
Demographics and Catchment Area
The primary catchment encompasses Bukit Bintang and surrounding KLCC areas, serving a population of 1.5 million within a 5 km radius, characterized by urban professionals aged 25-44, families with children, and expatriates. Median household income stands at RM7,500, supporting mid-market retail spend of RM150-250 per visit. Tourist influx, with 16.5 million visitors to KL in 2024, contributes 40% of footfall, favoring experiential categories like F&B and entertainment. Drawbacks include income polarization, where lower segments prefer nearby wet markets, and seasonal dips during monsoon (Nov-Feb) reducing outdoor-linked traffic by 15%. Data from NAPIC indicates 60% local vs 40% tourist demographic split, influencing demand for affordable international brands over luxury.
Competitive Landscape
Berjaya Times Square faces intense competition from 10+ malls in Bukit Bintang, including Pavilion KL (upscale, 95% occupancy) and Sungei Wang Plaza (value fashion hub). Proximity (within 500m) leads to 20-25% footfall cannibalization, per Cushman & Wakefield Q1 2025 report. Strengths lie in unique theme park integration, drawing 30% family traffic vs competitors 10-15%, but weaknesses include dated aesthetics and weaker anchor tenants compared to Suria KLCCs high-end mix. Market saturation risks further vacancy pressure with 4.2 million sq ft new supply in 2025, potentially eroding rents by 5%. Neutral positioning as a mid-tier option sustains 80% category overlap with peers, yet requires targeted promotions to counter e-commerce growth eroding 10% physical sales annually.
Lease Terms and Operational Metrics
Base rents range RM12-15 psf/month for ground floor spaces, escalating to RM8-10 psf on upper levels, with average lease terms of 3-5 years and 5% annual escalations, per Henry Butcher 2025 outlook. Turnover rent clauses at 6% of gross sales above RM1,000 psf threshold incentivize performance but expose tenants to volatility amid 3.64% CAGR retail growth forecast to 2030. Occupancy at 85% reflects stable operations, with footfall of 10 million annually supporting sales productivity of RM800-1,000 psf. Challenges include higher utility costs (RM2-3 psf) due to aging HVAC systems and competition-driven marketing spends at 2-3% of turnover. JLL notes positive rental reversions of 7% in 2024, but risks from economic slowdowns could cap upside, advising tenants to negotiate fit-out contributions up to RM200 psf.
Building Details
Detailed Market Analytics
City Snapshot
Kuala Lumpur
Comprehensive market intelligence for retail expansion in this city
Other Retail Destinations in Kuala Lumpur
Discover more shopping centers in Kuala Lumpur.
Popular in Malaysia
Top retail destinations across Malaysia.




Interested in this property?
Choose how you'd like to proceed
Advertise at this property?
Reach high-intent shoppers across digital screens, atria, and experiential placements.
City Snapshot
Kuala Lumpur
Comprehensive market intelligence for retail expansion in this city